
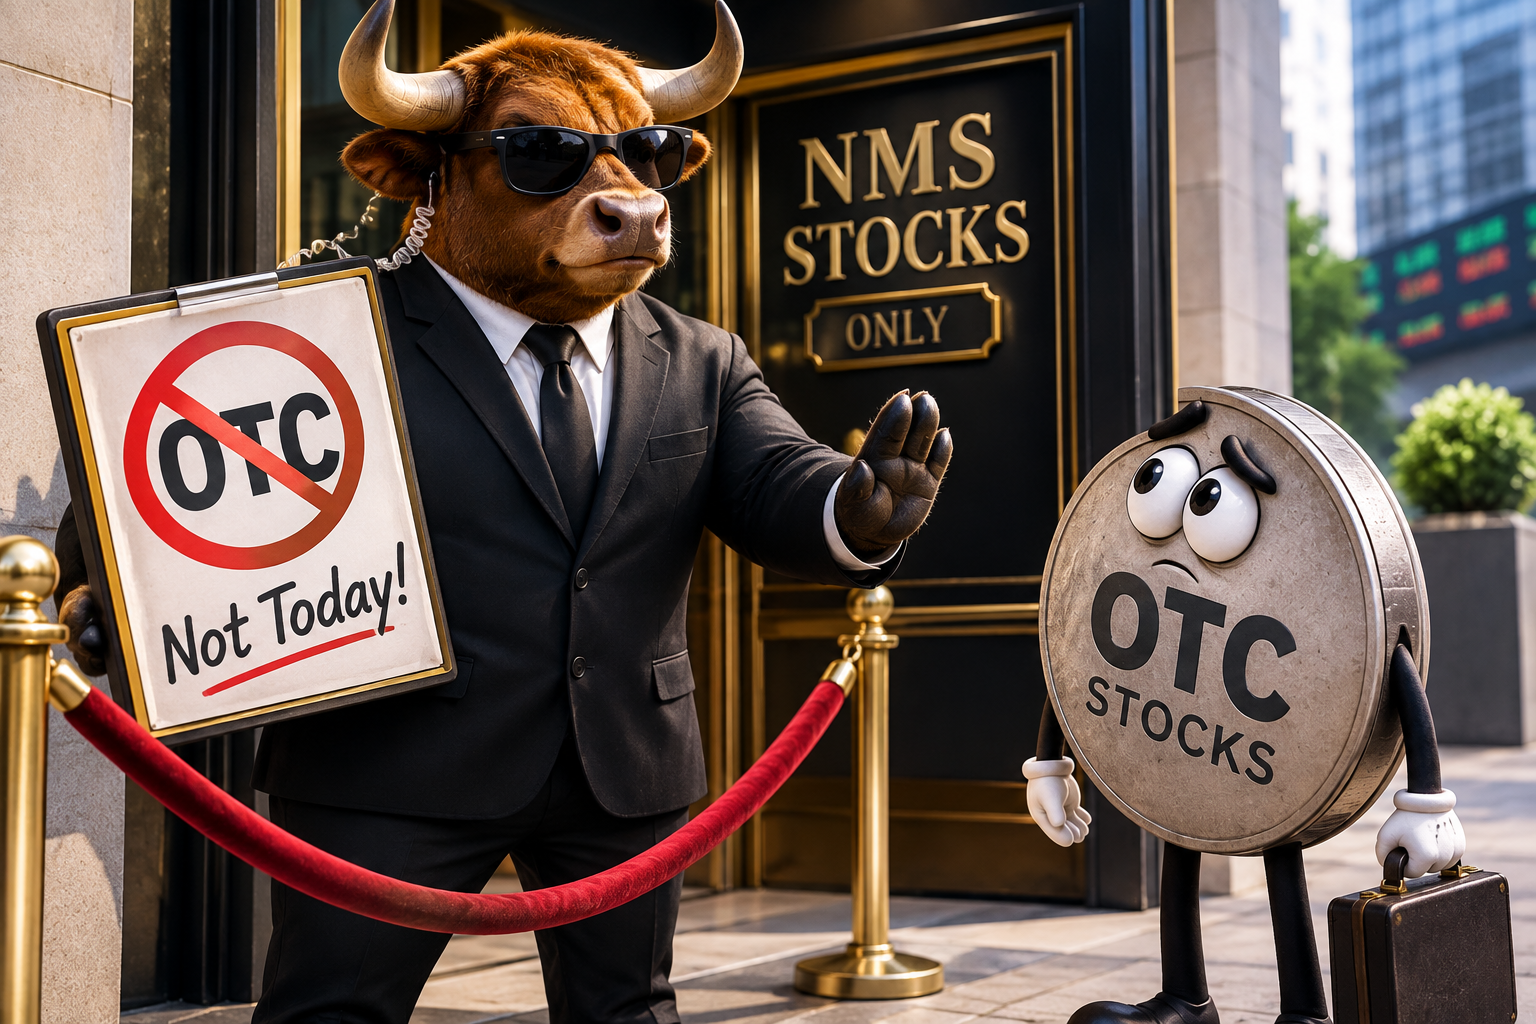
Yesterday, September 17, 2026, the Securities and Exchange Commission adopted a temporary, conditional Innovation Exemption intended to facilitate the onchain trading of certain tokenized stocks. Despite its broad-sounding name, the exemption does not apply to all tokenized securities, all public companies, or securities quoted on OTC Markets. It is narrowly limited to tokenized National Market System stocks – generally, stocks listed on national securities exchanges such as Nasdaq, the New York Stock Exchange, and NYSE American.
For companies whose securities are quoted on OTCQX, OTCQB, or OTCID, the distinction is critical. Those securities generally are not National Market System stocks and therefore are not eligible for trading under the SEC’s new Innovation Exemption.
What the SEC Innovation Exemption Does
The SEC’s September 17, 2026 order grants temporary, conditional relief from two specific provisions of the Securities Exchange Act of 1934:
- Certain Tokenized Securities Venues receive relief from the statutory definition of an exchange.
- Certain liquidity providers using proprietary capital in automated market maker liquidity pools receive relief from the statutory definition of a dealer.
The exemption allows a qualifying Tokenized Securities Venue to facilitate permissioned trading of tokenized National Market System stock through automated market makers and liquidity pools deployed on a public, permissionless distributed ledger.
The exemption is scheduled to remain available for five years, subject to its conditions and any future SEC action.
Meaning of Tokenized National Market System Stock
The exemption defines Tokenized NMS Stock as a National Market System stock that has been tokenized either:
- By or on behalf of the issuer of the underlying stock; or
- By an unaffiliated third party.
The tokenized stock must provide its holders with the same rights and privileges as the corresponding traditional stock. These rights generally include:
- The same economic interest in the issuer;
- The same dividend rights;
- The same voting rights; and
- The same rights to residual assets upon liquidation.
The exemption does not cover a separate crypto asset that merely provides synthetic exposure to a stock. It also does not cover tokenized linked securities, tokenized security-based swaps, rights, or warrants.
Why the Innovation Exemption Does Not Apply to OTC Markets Securities
The exemption is limited to tokenized National Market System stock. Securities quoted on OTC Markets generally do not fall within that definition.
A National Market System security is a security for which transaction reports are collected, processed, and made available through an effective national market system transaction-reporting plan. As a practical matter, this generally means an exchange-listed stock.
A security quoted on OTCQX, OTCQB, or OTCID does not become a National Market System stock merely because:
- The issuer files reports with the SEC;
- The security is registered under Section 12(g) of the Exchange Act;
- The issuer is current in its SEC or alternative reporting obligations;
- The security is eligible for public quotation;
- A broker-dealer reports transactions in the security to the Financial Industry Regulatory Authority; or
- The issuer intends to apply for a future Nasdaq or New York Stock Exchange listing.
Accordingly, an issuer whose common stock is quoted only on OTC Markets cannot rely on the Innovation Exemption to have that stock traded in tokenized form on a Tokenized Securities Venue.
The Exemption Applies to the Security Rather Than the Entire Company
The correct analysis focuses on the particular class of securities, not simply whether the issuer is a listed company.
If a company has one class of common stock listed on Nasdaq and another class quoted on OTC Markets, the exemption could potentially apply to the Nasdaq-listed class if all conditions are satisfied. It would not automatically extend to the separate class quoted on OTC Markets.
Likewise, an issuer’s plan to uplist does not make its existing securities National Market System securities. The applicable class must first become exchange-listed and otherwise satisfy the requirements of the SEC’s order.
SEC Reporting Status Is Not Enough
Some issuers incorrectly assume that filing Forms 10-K, 10-Q, and 8-K makes their securities exchange-listed. It does not.
An issuer may be subject to SEC reporting requirements while its securities remain quoted exclusively on OTC Markets. Exchange Act registration and national securities exchange listing are separate concepts.
Therefore, a reporting company whose securities are quoted on OTC Markets remains outside the scope of the Innovation Exemption unless and until the relevant class is listed on a national securities exchange and becomes National Market System stock.
The Limited Issuer Objection Right
The Innovation Exemption creates a limited issuer-notice and objection procedure, but it is not a general issuer veto over all tokenization activities.
Before a Tokenized Securities Venue may begin trading National Market System stock tokenized by an unaffiliated third party, the venue must provide written notice to the issuer of the underlying stock. Trading cannot begin for at least 30 calendar days after the issuer receives the notice.
If the issuer submits a written objection within that 30-day period, the Tokenized Securities Venue cannot make that tokenized stock available for trading under the exemption.
That objection right applies only when:
- The underlying security is National Market System stock;
- An unaffiliated third party tokenizes the stock; and
- The tokenized stock will be traded on a Tokenized Securities Venue relying on the Innovation Exemption.
The order does not create a universal issuer right to approve or reject every digital asset that mentions, references, or has some relationship with the issuer. It also does not extend this objection procedure to securities quoted exclusively on OTC Markets.
The Innovation Exemption Is Not a General Crypto Safe Harbor
The order does not determine whether a separate utility, governance, or ecosystem token is a security. It also does not exempt the offer or sale of such a token from the federal securities laws.
A native digital token does not fall within the exemption merely because:
- It is associated with a public company;
- Its developers describe it as a utility or governance token;
- It has a fixed supply;
- It will operate on a blockchain;
- It can be used in the same ecosystem as tokenized stocks; or
- It may eventually trade in a pair with a tokenized stock.
A non-security crypto asset may be paired with tokenized National Market System stock on a qualifying Tokenized Securities Venue. However, the crypto asset must independently qualify as a non-security. The Innovation Exemption does not provide that classification or protect the asset’s prior issuance, sale, promotion, or distribution.
Whether a digital token is a security continues to depend on its actual economic characteristics, the manner in which it is offered and sold, the representations made to purchasers, and the extent to which purchasers reasonably expect profits from the essential managerial efforts of others.
The Exemption Does Not Permit Primary Offerings
The Innovation Exemption concerns secondary-market trading. It does not authorize a company to conduct an initial or primary offering of tokenized stock on a Tokenized Securities Venue.
The SEC’s order expressly provides that:
- Primary issuances and initial offerings are not permitted under the exemption; and
- Offers and sales of tokenized National Market System stock must be registered under the Securities Act of 1933 or qualify for an available exemption from registration.
An issuer therefore cannot use the Innovation Exemption as a substitute for a registration statement, Regulation A offering, Regulation D offering, Regulation Crowdfunding offering, or another available Securities Act exemption.
Other Federal Securities Laws Continue to Apply
The relief is limited to specified provisions concerning the definitions of exchange and dealer. It does not eliminate other regulatory requirements.
The SEC’s order does not provide relief from:
- Securities Act registration requirements;
- The antifraud provisions of the federal securities laws;
- Section 10(b) of the Exchange Act and Rule 10b-5;
- Anti-manipulation requirements;
- Applicable broker-dealer registration requirements;
- Investment Company Act requirements;
- Anti-money-laundering obligations;
- Economic and trade sanctions; or
- Applicable state securities laws.
The SEC also requires Tokenized Securities Venues relying on the exemption to comply with numerous operational, notice, recordkeeping, access, disclosure, trading-volume, and investor-protection conditions.
Tokenization by an OTC Markets Company
An issuer whose securities are quoted on OTC Markets may be able to explore tokenization under the existing federal securities laws. However, it cannot rely on the September 17 Innovation Exemption for a class of securities that is not National Market System stock.
Any proposed tokenization would require a separate analysis of issues that may include:
- Securities Act registration or an available exemption;
- Exchange Act registration requirements;
- Broker-dealer involvement;
- Exchange or alternative trading system registration;
- Transfer-agent requirements;
- Clearing and settlement;
- Custody;
- State securities laws;
- Restrictions on secondary trading;
- Shareholder-record and beneficial-ownership issues; and
- Whether the digital instrument represents the actual security or merely provides synthetic exposure to it.
Tokenization changes the technology used to represent or transfer an asset. It does not, by itself, change the asset’s legal status or eliminate the securities laws applicable to its issuance and trading.
Effect of a Future Uplisting
If the relevant class of stock later becomes listed on Nasdaq, the New York Stock Exchange, or another national securities exchange, that class could become National Market System stock.
At that point, its tokenized equivalent might qualify for trading under the Innovation Exemption, provided that the Tokenized Securities Venue, tokenized security, liquidity providers, and trading activity satisfy all applicable conditions.
The possibility of a future uplisting does not bring the security within the exemption before the exchange listing becomes effective.
Frequently Asked Questions About Tokenized Stocks and OTC Markets
Does the SEC Innovation Exemption apply to OTCQX securities?
Generally, no. A security quoted on OTCQX is not National Market System stock merely because the issuer satisfies OTCQX standards or files reports with the SEC.
Does the exemption apply to OTCQB securities?
Generally, no. OTCQB quotation does not constitute listing on a national securities exchange and does not make the security National Market System stock.
Does the exemption apply to OTCID securities?
Generally, no. Securities quoted on OTCID are outside the exemption unless the particular security also independently qualifies as National Market System stock.
Does SEC reporting status make a company eligible?
No. SEC reporting status and exchange listing are separate. The exemption applies to the particular class of National Market System stock, not merely to companies that file reports with the SEC.
Can an OTC Markets company use the exemption for a utility or governance token?
Not merely because the token is associated with the company. The exemption does not determine whether a utility or governance token is a security and does not exempt its offer or sale.
Can an issuer object to an unaffiliated party tokenizing its stock?
The order provides a 30-day objection procedure when an unaffiliated third party tokenizes National Market System stock for trading on a Tokenized Securities Venue relying on the exemption. It does not create a general objection right for securities quoted exclusively on OTC Markets or for unrelated crypto assets.
Does the exemption allow a company to sell newly issued tokenized stock?
No. The exemption does not permit primary issuances or initial offerings on a Tokenized Securities Venue.
Key Takeaways for OTC Markets Issuers
The SEC’s Innovation Exemption represents a significant development for tokenized stocks, but its scope is narrow:
- It applies to tokenized National Market System stock, not securities quoted exclusively on OTC Markets.
- It applies to the particular class of security, not automatically to every security issued by an exchange-listed company.
- SEC reporting status does not make a security eligible.
- A planned uplisting is insufficient until the exchange listing becomes effective.
- The issuer-objection procedure is limited to unaffiliated third-party tokenization of National Market System stock under the exemption.
- The exemption does not determine whether a separate utility or governance token is a security.
- It does not permit primary offerings or eliminate Securities Act registration requirements.
- Antifraud, anti-manipulation, broker-dealer, and other securities-law requirements remain applicable.
Conclusion
The SEC’s September 17, 2026 Innovation Exemption is a targeted measure for the secondary trading of tokenized exchange-listed stocks. It is not a general exemption for tokenized securities, blockchain projects, crypto assets, or public companies.
Most importantly for smaller public companies, securities quoted exclusively on OTC Markets do not qualify merely because the issuer is publicly traded, files reports with the SEC, or plans to uplist. Those issuers must continue to evaluate tokenization under the existing federal and state securities-law framework.
Companies considering tokenized stocks or digital assets should obtain securities counsel before issuing tokens, promoting token-related investment opportunities, establishing liquidity arrangements, or representing that a token or trading venue qualifies for the SEC’s Innovation Exemption.
This article is general information, not legal or financial advice.
To speak with a Securities Attorney, please contact Brenda Hamilton at 200 E Palmetto Rd, Suite 103, Boca Raton, Florida, (561) 416-8956, or by email at [email protected].
Hamilton & Associates | Securities Attorneys
Brenda Hamilton, Securities Attorney
200 E Palmetto Rd, Suite 103
Boca Raton, Florida 33432
Telephone: (561) 416-8956
Facsimile: (561) 416-2855
www.SecuritiesLawyer101.com