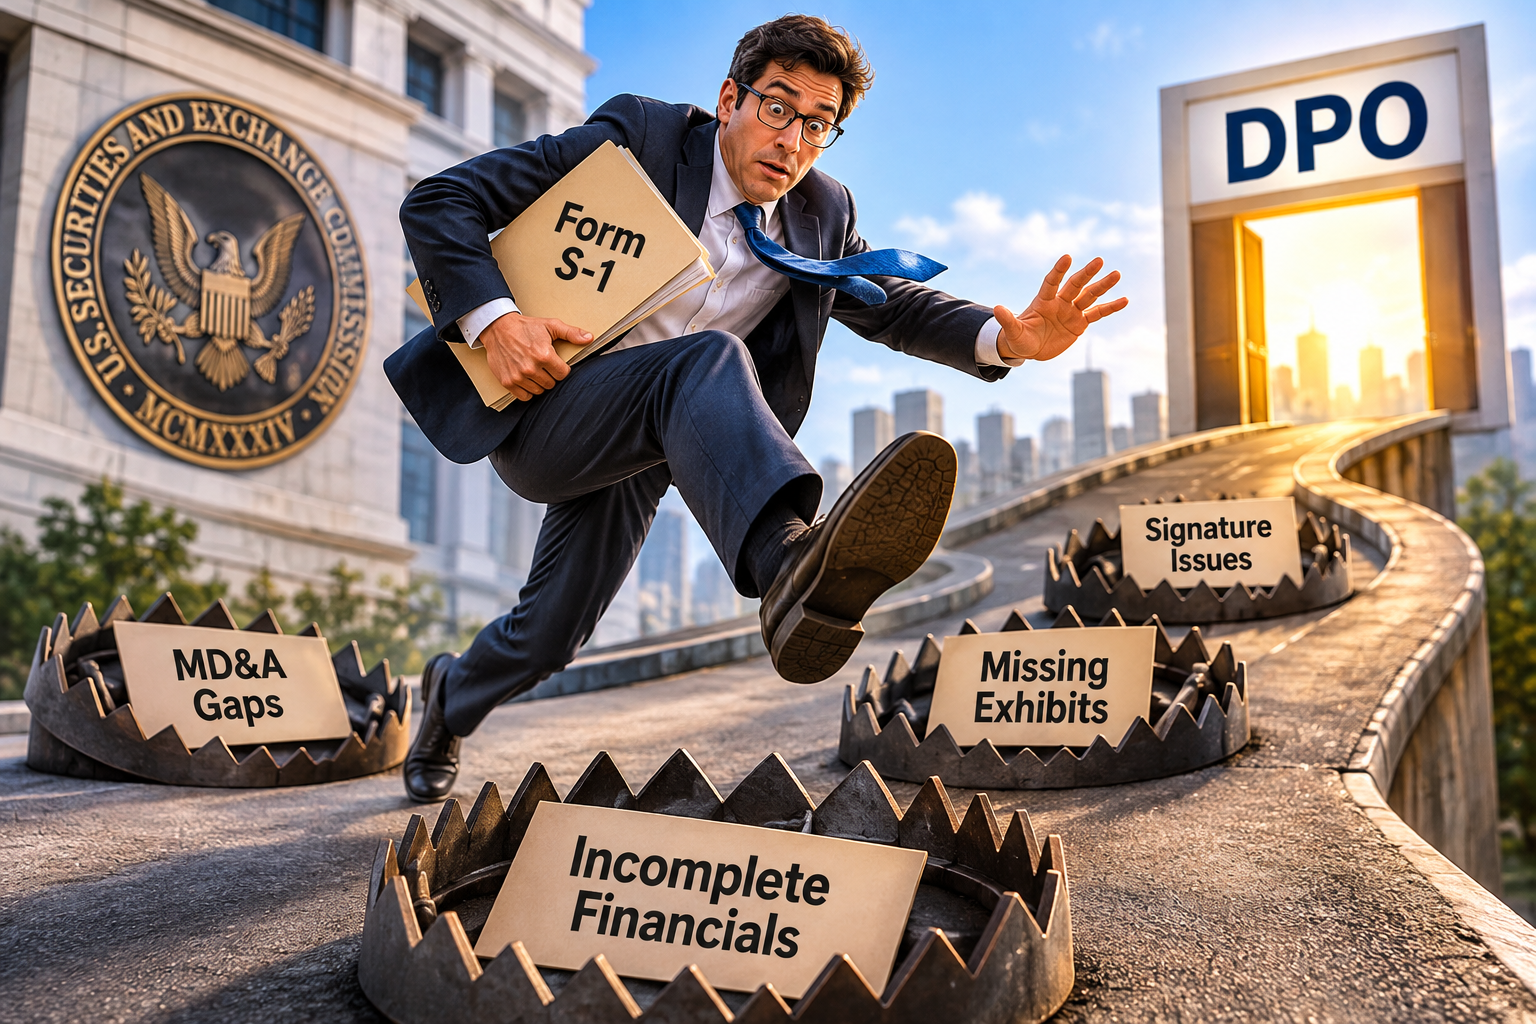
For companies pursuing a Direct Public Offering (DPO), few moments are as critical as the SEC’s declaration of effectiveness on Form S-1. This milestone allows the issuer to sell securities to the public and move toward quotation. Yet many issuers encounter avoidable delays during SEC review—delays that often stem from technical errors, incomplete disclosures, or inconsistencies in financial statements, MD&A, signatures, and exhibits.
1. Incomplete or Non-Compliant Financial Statements
Financial reporting errors are the most common source of SEC delays. The SEC requires current, accurate, and audited financial statements.
- Outdated Financial Statements — Financials must be current as of the filing date and remain current through effectiveness.
- Missing or Incorrect Audit Reports — Form S-1 requires audited statements from a PCAOB-registered accounting firm with proper signatures and independence statements.
- Inconsistent Numbers — Discrepancies in revenue, net income, or share counts between sections prompt SEC comments.
2. Weak or Boilerplate MD&A Disclosures
The Management’s Discussion and Analysis (MD&A) section is among the most scrutinized portions of Form S-1. Many issuers restate financial data without explaining underlying causes or trends.
- Lack of Analysis — MD&A must explain causes of material changes, not repeat financial results.
- Missing Liquidity Discussion — The SEC expects analysis of cash flow adequacy and funding plans.
- Omitted Going Concern Disclosures — If auditors express doubt, issuers must address it directly in MD&A.
3. Signature and Filing Deficiencies
Form S-1 is a formal certification document, and missing or improper signatures can halt the review process entirely.
- Missing Signatures — Form S-1 must be signed by the principal executive, financial, and accounting officers, plus a majority of directors.
- Incorrect or Unverified Signatures — Conformed or digital signatures must have manual authorization retained under Regulation S-T.
4. Exhibit and Legal Opinion Problems
Exhibit-related errors are another frequent source of SEC delays. All required exhibits must be filed before the Commission will declare the registration effective.
- Missing Exhibits — Material contracts, auditor consents, and legal opinions are often omitted.
- Legal Opinion Errors — Opinions must confirm that the securities are legally authorized, validly issued, fully paid, and non-assessable.
5. Inconsistent or Misleading Risk Factors
Risk factors must be specific, material, and consistent with MD&A disclosures. Generic or boilerplate risks invite SEC comment and delay.
- Generic Risks — Avoid copy-paste language that lacks issuer specificity.
- Missing Emerging Risks — The SEC expects inclusion of current risks such as cybersecurity or supply chain issues.
- Internal Inconsistencies — Ensure risk factors align with MD&A and financial disclosures.
6. Procedural Pitfalls in the Filing Process
Even well-prepared filings can stall due to procedural missteps. Correct form types, amendments, and acceleration requests are essential.
- Incorrect EDGAR Form Type — Verify that the filing uses the correct form designation (e.g., S-1, not S-1MEF).
- Failure to Update Delaying Amendments — Ensure amendments are filed and clearly redlined.
- Premature Acceleration Requests — Wait until all comments and exhibits are cleared before requesting effectiveness.
7. Communication and Response Delays
Timely, complete responses to SEC comment letters are essential. Delayed or incomplete replies prolong the review process.
- Respond promptly and address each comment by reference to the amended filing.
- File response letters concurrently with Form S-1/A amendments on EDGAR.
8. Common SEC Focus Areas for DPOs
- Financial Statements: GAAP compliance, revenue recognition, related-party disclosures
- MD&A: Liquidity analysis and trend discussion
- Exhibits: Missing contracts or unsigned opinions
- Signatures: Incomplete or incorrect director signatures
- Risk Factors: Generic, inconsistent, or outdated disclosures
- Corporate Governance: Missing audit committee or ethics code
- Offering Details: Incomplete use of proceeds or offering terms
9. Avoiding the Pitfalls: Best Practices
- Engage experienced securities counsel familiar with SEC DPO reviews.
- Cross-check all data for consistency before submission.
- Prepare exhibits and consents in advance.
- Draft a detailed, analytical MD&A using plain English.
- Verify all signatures and authorization letters under SEC rules.
- Respond promptly to SEC comment letters.
Conclusion: Avoiding Delays by Getting It Right the First Time
The SEC’s review of a DPO is rigorous but predictable. Most delays stem from avoidable issues in financials, MD&A, signatures, and exhibits. Issuers who prepare carefully, ensure accuracy, and maintain transparent communication can achieve faster SEC clearance and build investor confidence.
This article is for informational purposes only and should not be construed as legal advice.
About the Author
Brenda Hamilton is a securities attorney with Hamilton & Associates Law Group, P.A.
Hamilton & Associates Law Group, P.A. | Securities Lawyer 101
To speak with a Securities Attorney, please contact Brenda Hamilton at 200 E Palmetto Rd, Suite 103, Boca Raton, Florida, (561) 416-8956, or by email at [email protected].
Hamilton & Associates | Securities Attorneys
Brenda Hamilton, Securities Attorney
200 E Palmetto Rd, Suite 103
Boca Raton, Florida 33432
Telephone: (561) 416-8956
Facsimile: (561) 416-2855
www.SecuritiesLawyer101.com